Skip to content
San DiegoHome Appraisal & Valuation

California

Retail Property Appraisal

Updated November 17, 2026

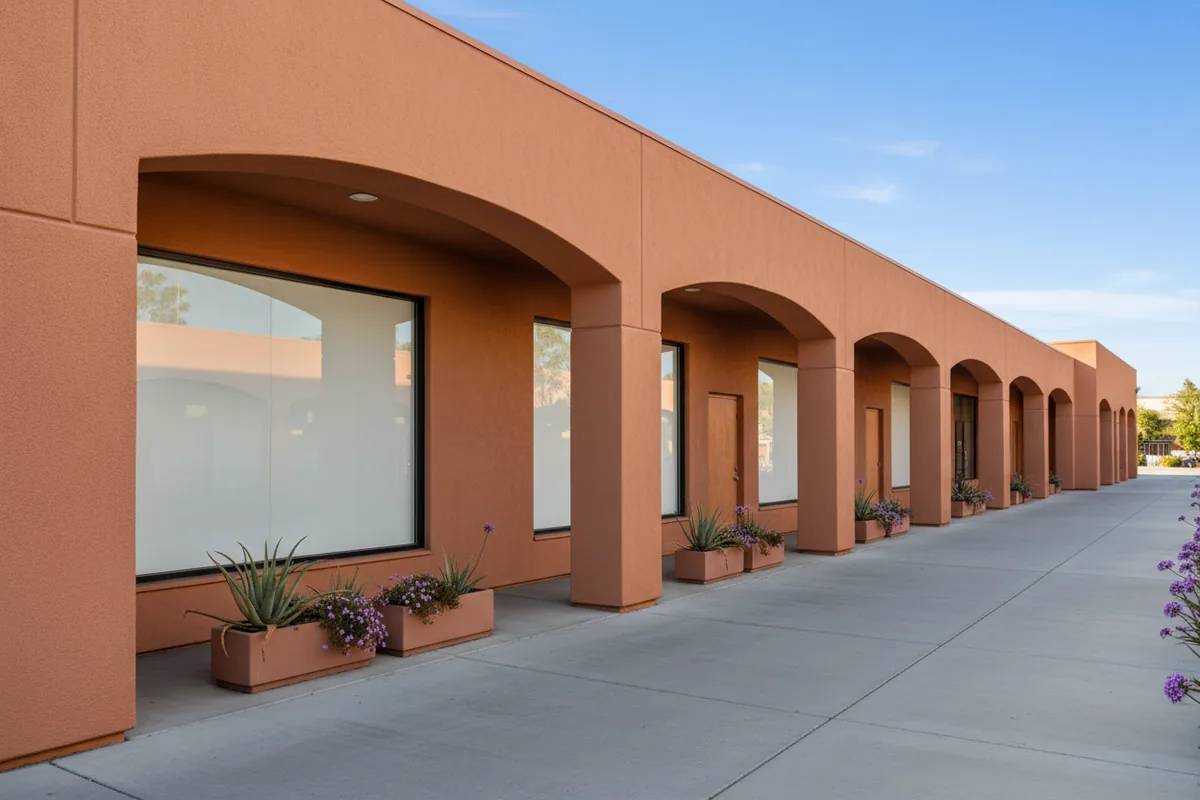
A covered walkway past blank storefronts, the retail strip whose market value is appraised.
Immediate answer

A retail property appraisal is a formal, written opinion of what a store building, strip center or shopping center would sell for on the open market. A state-credentialed appraiser prepares it. It is different from the county's assessed value, a real estate agent's market analysis or an online estimate. Lenders, courts and tax authorities generally look for this kind of report.

On this page
  1. Key Takeaways
  2. When This Option Fits
  3. How It Works, Step by Step
  4. Costs, Timing and Trade-offs
  5. Options to Compare
  6. What to Have Ready
  7. Local Context
  8. Frequently asked questions

You may own a strip center in El Cajon, hold a single-tenant building through a family trust, or serve as the executor of an estate that includes a neighborhood shopping center. You may also be a spouse dividing property in a divorce. In each case a sale, a refinance, an estate filing or a property tax question now turns on one number, and the people involved need that number to hold up. Retail property makes the question harder than it is for a house. The value depends on leases, tenants and income as much as on the building, and a quick figure from a website rarely accounts for any of them.

This page describes what a retail property appraisal in San Diego County involves, when an owner or another party usually needs one, how the work proceeds, and how it compares with the other valuation tools available.

Key Takeaways

  • Who prepares it. A retail property appraisal is prepared by a state-credentialed appraiser. In California, the California Bureau of Real Estate Appraisers (BREA) credentials appraisers.
  • What it covers. Retail property includes strip centers, neighborhood shopping centers and single-tenant retail buildings throughout San Diego County.
  • How it is valued. Leases, tenants and income drive retail value, so the analysis usually centers on the income approach alongside comparable sales.
  • Other figures. Assessed value, an agent's comparative market analysis (CMA) and an automated valuation model (AVM) each serve a purpose, but none is an appraisal.
  • Cost. Fees vary with the property and the purpose of the report. A single-tenant building and a multi-tenant shopping center involve very different amounts of work.

When This Option Fits

A formal appraisal fits when someone outside the owner's own circle needs to rely on the value. Common situations in San Diego County include:

  • A sale or purchase of a retail property or shopping center.
  • A refinance. Lenders typically require a formal appraisal before they lend against a retail property.
  • Estate, probate or trust administration when a retail property is among the assets. The trust property appraisal and inherited property appraisal topics cover related ground.
  • Divorce or dissolution when a retail property is a marital asset.
  • A property tax appeal when an owner believes the Assessor's assessed value does not reflect market value.
  • A partnership dissolution or buy-sell agreement that calls for a valuation.
  • Eminent domain or condemnation, when a public agency acquires private property.

The purpose of the appraisal matters. An appraisal for a lender, an estate, a tax appeal or a lawsuit may use a different value standard or effective date, and the appraiser sets the scope to match. When co-owners, a lender or an agency disagree with the owner, or a case has been filed, the dispute itself is a separate matter for an attorney. The litigation property appraisal topic covers appraisals prepared for those settings.

A home value review or market estimate is a different, informal product.

How It Works, Step by Step

An individual appraiser may vary the order or the detail.

1. Request. The owner or another authorized party asks for an appraisal and supplies the basics: the address, the property type and the intended use of the report. 2. Scope of the engagement. The appraiser confirms three things: the intended use, the value standard (usually market value) and the effective date, which is the date the value speaks to. 3. Inspection. The appraiser inspects the property. This includes building condition, tenant spaces, the site and access. 4. Data collection. The appraiser gathers rent rolls, lease abstracts (short summaries of each lease's key terms) and income and expense data. The appraiser also collects comparable sales and leases from San Diego County. 5. Valuation analysis. Retail property is usually analyzed in more than one way: - The income approach converts the property's net operating income (rent and other income less operating expenses) into a value. - The sales comparison approach looks at what similar retail properties sold for. - The cost approach, used in some cases, estimates what it would cost to replace the building, less wear, plus the land. 6. Report. The appraiser prepares a written report. A summary-style report states the conclusions and the key support briefly. A narrative report sets out the data and reasoning in full.

The Appraisal Institute publishes consumer material on what appraisals involve at appraisalinstitute.org. Owners who want a general background on the process often start there.

Costs, Timing and Trade-offs

The size and complexity of the property drive cost. A single-tenant building on a net lease, where the tenant pays most operating costs, usually involves fewer documents and less analysis than a multi-tenant shopping center in San Diego County. A center with many leases, anchor tenants and shared common-area costs takes more work.

Several other factors also affect the cost:

  • the size of the property and the number of tenants;
  • how complete and available the lease and income records are;
  • the intended use, such as lending, estate administration or litigation;
  • the report type, summary or narrative.

Timing depends on the same factors. A well-documented single-tenant property generally moves faster than a center with incomplete records or a report prepared for court.

A formal appraisal costs more and takes longer than an online estimate or a broker's opinion. In exchange, it produces a documented opinion that lenders, courts and tax authorities generally accept. For an owner facing an estate deadline or a loan condition, the slower and more thorough report is usually the one the other side is asking for.

Options to Compare

Each valuation tool has a real use and real limits.

OptionWho prepares itWhere it is usedLimits
Formal appraisalA state-credentialed appraiserLending, courts, IRS and tax mattersHighest cost and longest timeline of the four
Broker's opinion of value (BOV), broker price opinion (BPO) or comparative market analysis (CMA)A real estate agent or broker, comparing recent salesInternal planning and pricing discussionsLess formal; not accepted for most lending or legal purposes
Automated valuation model (AVM)An algorithmA quick reference pointLess reliable for retail than for single-family homes; not an appraisal
Assessed valueSan Diego County AssessorProperty taxA Proposition 13 base-year value adjusted annually, not necessarily current market value

Assessed values appear in the public records of the San Diego County Assessor-Recorder-County Clerk at sdarcc.gov.

When the decision is whether to sell, a value opinion is only half of it. Estimated net proceeds also matter: the price less commissions, repairs, carrying costs, loan payoffs and closing costs. Comparing the appraisal against those net figures is how an owner tells which path fits the situation.

What to Have Ready

An appraiser can work faster and more accurately when the records are organized at the start. A practical starting set includes:

  • Property address and legal description. The legal description appears on the deed.
  • Current rent roll. This lists the tenants, lease terms, base rent and any percentage rent, which is rent tied to a tenant's sales.
  • Copies of current leases, along with any amendments.
  • Income and expense statements.
  • The most recent property tax bill from the San Diego County Treasurer-Tax Collector.
  • Any recent sale, purchase or listing agreements for the property.
  • A survey or site plan, if one is available.
  • Prior appraisal reports, if any exist.
  • Notes on deferred maintenance, capital improvements and pending lease changes, such as a tenant leaving or a renewal under negotiation.

The appraiser may ask for more after reviewing the first set of documents, especially for a shopping center appraisal with many tenants. For an executor or trustee, gathering leases that a prior owner kept can be the slowest part of the work. Starting early leaves room to find them.

Local Context

Retail property across San Diego County covers very different markets. Downtown San Diego storefronts, Mission Valley centers, strip centers in Chula Vista and National City, East County properties in El Cajon and La Mesa, and North County centers in Escondido, Oceanside and Carlsbad each respond to their own tenant mix, traffic and demand. A strip center in Chula Vista and a neighborhood center in Carlsbad may carry different capitalization rates and different value drivers. Those differences are why comparable sales and leases are drawn from the relevant submarket rather than from the county as a whole. The Chula Vista property appraisals topic describes one of these local markets.

Several public offices hold the records an appraisal relies on:

  • San Diego County Assessor-Recorder-County Clerk (sdarcc.gov) maintains property records, assessed values and ownership information for retail properties in the county.
  • San Diego County Treasurer-Tax Collector (sdttc.com) handles property tax billing and payment records.
  • San Diego Superior Court hears probate, divorce and eminent domain matters; for a decedent domiciled in California, probate belongs in "the county in which the decedent was domiciled, regardless of where the decedent died."
  • California Bureau of Real Estate Appraisers (brea.ca.gov) credentials the appraisers who may work on these properties.

Setting the property's current record and assessed value from the Assessor-Recorder-County Clerk beside the most recent rent roll shows how far the tax figure sits from what the leases suggest the property earns.

Take the next step

Ready to take the next step with your property?

Tell us about the property and why you need an appraisal, so an independent appraiser can confirm the right scope of work.

How it works

  1. The propertyIts address and its type.
  2. The purposeA sale, an estate or probate, a divorce, a trust, tax or a legal matter.
  3. Your timelineWhen the appraisal is needed.

How we work

  • Every request is reviewed by a person. Nothing on this site calculates a value automatically.
  • Appraisals are prepared by independent, state-licensed or certified appraisers, never by this website.
  • Estimates and cash offers are clearly labeled — never presented as appraisals.
  • A request does not commit you to anything.

Frequently asked questions

How do I check the value of a retail or commercial property?

A formal appraisal by a state-credentialed appraiser is the most defensible way to check it. The assessed value published at sdarcc.gov and online commercial tools can serve as reference points, though neither is an appraisal.

Does the seller find out the appraisal value?

That depends on who ordered it. The party who engages the appraiser is the client and receives the report. Whether a seller, buyer or lender sees it depends on who engaged the appraiser and on the terms of the engagement, so no single rule covers every transaction.

Is there a Zillow for commercial property?

Commercial automated valuation tools do exist. Because leases and income drive retail value, these tools are generally less reliable for retail properties than residential estimates are for houses.

How much does a retail property appraisal cost?

Cost varies with the property's complexity, the number of tenants, the availability of income data, the intended use and the report type. A single-tenant building generally involves less work than a multi-tenant center.

What is the difference between an appraisal and an assessed value?

An appraisal is an opinion of current market value. An assessed value is set by the San Diego County Assessor under Proposition 13 rules as a base-year value adjusted annually, so the two can differ. Assessed values appear at sdarcc.gov.

What does the California Bureau of Real Estate Appraisers do?

BREA is the state authority that credentials real estate appraisers in California. It publishes consumer information about appraiser credentialing at brea.ca.gov. That site is where an owner can learn more about the credentialing role behind an appraisal report.

When is a retail property appraisal required?

Common triggers include a sale or purchase, a refinance, estate or probate administration, divorce, a property tax appeal and a partnership dissolution. Lenders typically require one for a refinance. Beyond that, the requirement depends on the setting, because a lender, a court and a tax authority may each apply its own standard.

What is a shopping center appraisal?

A shopping center appraisal is a formal valuation of a multi-tenant retail property. It relies mainly on the income approach, which converts net operating income into value, and on the sales comparison approach. Multiple leases, anchor tenants and common-area costs usually make it more involved than a single-tenant appraisal.